All Categories
Featured

Building Family Financial Security Through Life Insurance
How does the 2026 subsidy cliff impact Pennsylvania family health insurance coverage? The return of the 400 percent FPL aid cliff in 2026 around $128,600 yearly earnings for a family of 4 considerably increased expenses for middle-income Pennsylvania households on Pennie.
Even households above the APTC threshold might have kids eligible for CHIP if household earnings is listed below 319 percent FPL per-child, significantly lowering overall household protection expense. Can Pennsylvania families enroll in CHIP outside of open registration?
Children who get eligibility due to earnings changes, loss of other coverage, or other scenarios can be enrolled in CHIP at any point during the year. CHIP, Medical Support, and Pennie marketplace strategies frequently work together for Pennsylvania families.'s certified PA brokers confirm eligibility for every single family member and total enrollment at no additional expense.
is not connected with Pennie, the Pennsylvania Department of Human Being Services, the Pennsylvania Insurance Coverage Department, or any provider consisting of CHIP providers. The firm assists Pennsylvania residents compare plans and enroll in coverage at no extra expense.
An insurance coverage program jointly moneyed by states and the federal government that provides health insurance coverage to low-income children and, in some states, pregnant females in households who make too much earnings to get approved for Medicaid but can not pay for to acquire private health insurance coverage.
Insurance in Lakewood CAUnderstanding PPO Vs HMO Plans
We learned the other day that the typical expense of a family medical insurance policy through a company reached almost $27,000 this year, 6% higher than what it cost in 2024. As if that weren't alarming enough, scientists are forecasting that the overall most likely will skyrocket towards $30,000 next year since of rising medical expenses and the relentless pressure insurance companies are under from Wall Street to increase their earnings.
Regardless of repeated assurances from insurance companies that we can count on them to hold down the cost of healthcare and consequently the premiums they charge there are now several years of evidence from researchers like KFF, which tracks annual modifications in employer-sponsored protection that they have not and can not provide on their promises.
A medical insurance policy today is usually less important than it was a decade ago since families have to spend more and more money out of their own pockets every year before their coverage kicks in. In addition, they are far more most likely to be notified that their insurance providers will not cover the care their doctors state they need.
That is a rate of boost much greater than basic inflation and also greater than medical inflation. Not only has the overall cost of an employer-sponsored plan increased, so has the share of premiums workers need to pay. This year, employers subtracted an average of $6,850 from their employees' paychecks for household protection, up from $4,823 in 2014, a 42% increase.
The Affordable Care Act, to its credit, instituted a cap on out-of-pocket expenses in 2014, but that cap has been increasing every year in addition to premiums. (The U.S. Department of Health & Person Providers sets the out-of-pocket max every year, pegging it to the average boost in premiums.)In 2014 the out-of-pocket cap for a household policy was $12,700.
Securing Low-Cost 2026 Family Health Insurance
And remember that the cap just uses to in-network care. If you head out of your insurance provider's network or take a medication not covered under your policy, you can be on the hook for hundreds or thousands more. While a lot of employer-sponsored plans have caps that are substantially lower, lots of people and households reach the legal max every year.
Jointly, those seven business made $71.3 billion in revenues in 2015 alone. That was up somewhat from $70.7 billion in 2023. Insurance providers stated their 2024 earnings were rather depressed since more of their health insurance enrollees went to the physician and got their prescriptions last year. Investors raged that insurance providers couldn't keep that from taking place, as you'll see in the charts listed below.
In general, the stock rates of the huge insurance coverage conglomerates have increased progressively over the years as we and our employers have had to invest more for policies that cover less. By contrast, the Dow Jones Industrial Average increased 139% (from $17,823.07 to $42,544.22), and the S&P 500 increased 186% (from $2,058.90 to $5,881.63) throughout the very same period.

Latest Posts
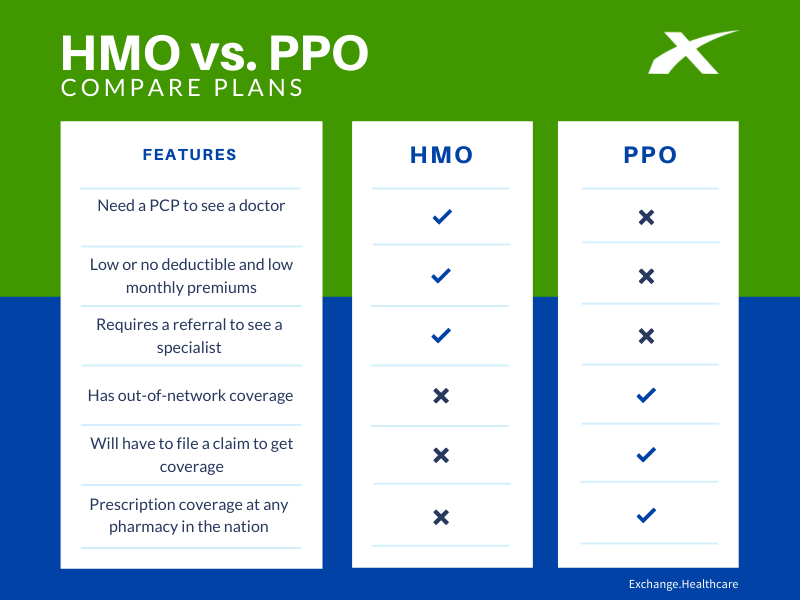
Evaluating PPO vs HMO Health Coverage

Final Expense and Burial Expense Planning
Optimizing Medicare Part D Coverage in 2026